

Subpilot

- 1.67K Reviews
- 4.1
- Downloads
- 100,000+
Our take on Subpilot from Appgk
Subscription costs are easy to underestimate because they rarely arrive as one dramatic payment. They sit quietly in the background, renew at different times, and often belong to services I no longer use regularly. Subpilot, a finance app from Linerios Limited, is built around that exact problem: helping me see recurring subscriptions and decide which ones are worth keeping. After spending time with it, I see the appeal immediately, but I also think its lasting value depends on whether you are willing to turn a quick cleanup into a regular money habit.
The app is free to install and aimed at everyone, with optional in-app purchases ranging from $4.99 to $99.99 per item. It has reached over 100 thousand installs and holds a 4.1 average from around 4.2 thousand ratings, which suggests a useful level of interest without making it seem universally loved. Its store summary is simple—track and cancel subscriptions—and that simplicity is important. This is not trying to replace a full banking app or become a complete budgeting system. Its job is narrower, and that can be a strength.
What Subpilot feels like after the first week
My first impression was that the app makes an irritating financial task feel more approachable. Subscription management is usually scattered across email receipts, bank statements, app-store pages, and memory. A dedicated place to review those commitments changes the question from “What did I pay this month?” to “What am I still choosing to pay for?” That small shift is the most convincing part of the experience.
The first week is where the novelty works in its favor. I can imagine opening the app with a vague suspicion that several small charges are slipping through, then finding enough structure to investigate them one by one. A music service used only during travel, a fitness membership opened for a short-term goal, or a cloud plan kept after a device upgrade can all look harmless individually. Together, they make a strong case for a subscription-focused review.
Best Parts of Subpilot
Things to Keep in Mind About Subpilot
What I like is that the app encourages a decision rather than merely displaying a number. A list of recurring services is useful, but the practical benefit comes from asking what each one does for me now. That makes Subpilot more valuable for people who have accumulated subscriptions gradually and no longer remember why each charge exists.
The first-week workflow is also a good test of expectations. I would not treat the app as an instant financial rescue tool. It cannot make an unwanted service disappear simply because I noticed it. Cancellation may still require visiting the original provider, an app marketplace, or a website. The useful contribution is helping me identify the target and giving me a more organized starting point.
News and Features Related to Subpilot

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic example is a household preparing for a tighter month. Instead of cutting randomly, I would use Subpilot to review recurring entertainment, storage, learning, and lifestyle services. I could separate essentials from “nice to have” subscriptions, check which ones are genuinely active, and cancel the least valuable commitments through their original channels. That is more sensible than reacting to a single unexpectedly high card statement.
There is another practical advantage during the first week: the app can act as a memory aid. I often remember a service by what I use it for, not by the company name appearing on a payment record. A subscription tracker gives that forgotten commitment a place in my attention. Even when I decide to keep a service, confirming that decision feels better than letting renewal happen unnoticed.
Don't want to read the full review?
The useful distinction between discovery and cancellation
One point deserves emphasis because it affects how I would use the app. Tracking and cancelling are related, but they are not the same job. Tracking is about building awareness and maintaining a list. Cancellation is an action that may depend on the merchant, payment route, account credentials, or renewal rules. I would use Subpilot for the first part and treat cancellation as a follow-through task rather than assuming the app handles every step end to end.
That distinction also answers a common concern: whether someone needs to understand finance before using it. I do not think so. The app is more suitable for ordinary household decisions than for advanced investing or detailed accounting. If you can recognize which services you use and which charges repeat, you have enough context to get value from it.
Screenshots
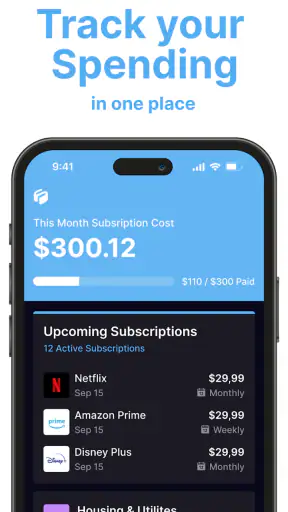
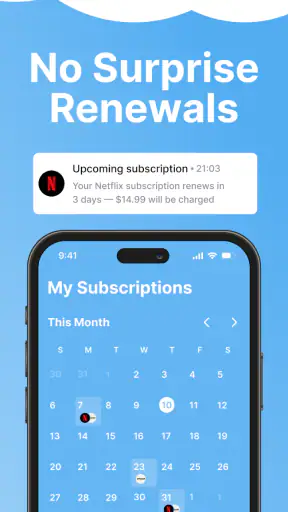
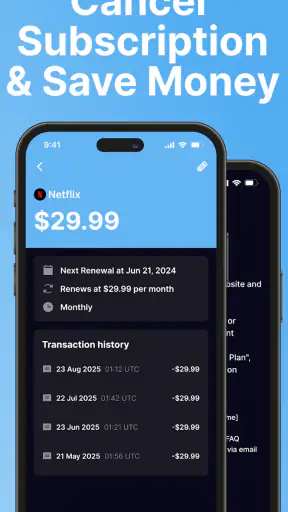
On the other hand, people who already maintain a careful spreadsheet may not feel an immediate need to switch. A spreadsheet can record renewal dates, monthly costs, and cancellation notes with great flexibility. Subpilot earns its place when a person wants a purpose-built experience and is more likely to review a focused app than an old document that is easy to forget.
Why the value may or may not survive the first month
The first review is satisfying because it reveals obvious waste. The harder question is what happens after the cleanup. Subscription tracking is not a one-time task: services change price, billing schedules move, trials become paid plans, and personal priorities shift. Subpilot has a chance to remain useful because recurring payments are an ongoing problem, but only if I return to it at sensible intervals.
I would build the app into a monthly money check rather than open it every day. A short review near the end of the month could cover new subscriptions, upcoming renewals, and services that have not been used. This avoids turning the app itself into another source of digital clutter. The goal is not constant monitoring; it is a reliable pause before recurring charges become invisible again.
For me, the strongest month-to-month use case is a change in routine. Moving home, changing jobs, starting a course, traveling, or adjusting a family budget can make old subscriptions suddenly less relevant. A service that made sense during a busy period may be unnecessary when circumstances change. Subpilot is most valuable when used alongside those life changes, because that is when forgotten payments are easiest to justify and hardest to notice.
A second non-obvious use is using the tracker before adding a new subscription. Instead of asking only whether I can afford the advertised monthly amount, I would first look at the commitments already running. That gives the new service a fairer place in the decision. Sometimes the right answer is not “I cannot afford this,” but “I already pay for something that does almost the same job.” This comparison can prevent duplication rather than merely clean it up later.
Families may also find the app useful as a conversation starter, although I would keep expectations realistic. Shared finances often contain services that one person uses and another person pays for. A subscription review can turn vague frustration into a concrete discussion: who uses it, how often, and whether the benefit justifies the recurring charge. The app does not replace agreement between people, but it can make the list easier to discuss.
Its long-term value is therefore behavioral. If I open it once, cancel two services, and never return, it has delivered a short-term win. If I use it to create a repeatable review habit, it becomes more defensible as a permanent finance tool. That is a higher standard than simple installation appeal, but it is the right standard for an app dealing with recurring expenses.
Where it fits beside ordinary alternatives
Compared with checking a bank statement, Subpilot offers a narrower and potentially clearer lens. Bank statements show money leaving, but they do not always make recurring commitments easy to group mentally. A subscription-focused app can reduce that search effort. The trade-off is that a bank statement remains the authoritative place to verify what was actually charged, so I would use both when a payment looks unfamiliar.
Compared with managing subscriptions separately through Apple, Google, or individual providers, Subpilot can provide a more unified review. The separate account pages are often the correct place to change or cancel a plan, but they encourage me to look at one provider at a time. A central overview is better for spotting the total pattern. If I only want to cancel one known service, going straight to that service may be faster.
Compared with a full budgeting app, Subpilot is less likely to overwhelm someone who wants one focused task. A complete budget can connect income, categories, goals, and spending history, which is better for broader financial planning. Subpilot makes more sense for the person whose main concern is recurring commitments. I would not choose it as my only money app if I needed detailed cash-flow forecasting or comprehensive household accounting.
A spreadsheet remains the best alternative for people who want custom fields, manual notes, and complete control. It can also be shared and adapted to unusual arrangements. Its weakness is maintenance discipline. Subpilot’s advantage is not that a list is impossible to create elsewhere; it is that a dedicated subscription review may be easier to revisit than a spreadsheet buried among other files.
The maintenance burden behind the convenience
Any tracker is only as accurate as the attention given to it. That is the main limitation I would explain to a friend before recommending Subpilot. Recurring payments can be billed annually, bundled with other services, charged under a parent company, or paid through a different account than expected. I would verify important entries against bank or card records rather than assuming that a neat list automatically means a complete list.
There is also a human maintenance burden. After cancelling a subscription, I would mark the decision clearly and then check the next relevant statement to make sure the charge has actually stopped. That extra check is not a criticism unique to Subpilot; it is simply good practice whenever cancellation involves another provider. The app can help me remember what to inspect, but it does not remove the need for confirmation.
The same applies to free trials and temporary plans. A trial is not necessarily wasteful, but it is easy to forget because the initial cost is zero. I would use the tracker as a prompt to record why I started the trial and what would make me cancel it. That simple note changes the decision from passive renewal to an intentional choice. It is one of the more useful ways to prevent the app from becoming just another list.
Privacy and access should also be considered before installing any finance app. I would read the permission and account screens carefully and decide whether the convenience is worth the information involved in setting it up. People who are uncomfortable connecting financial information, or who prefer manual tracking, may reasonably choose a spreadsheet instead. A subscription manager is not automatically the right answer for every level of financial sensitivity.
Device compatibility is fairly approachable: the current version is 1.24.1 and it requires Android 8.0 or later. That makes it practical for many Android users, including people who do not own a recent phone. I would still keep the app updated when possible, especially for a finance-related tool, because reliability matters more here than having the newest visual design.
What can cause fatigue over time
The first source of fatigue is repetition. If every review requires the same manual decisions without revealing anything new, I may stop opening the app. That is why I would schedule reviews around meaningful moments—before a major trip, after a move, at the start of a new work arrangement, or when reviewing a household budget—rather than forcing a daily routine.
The second is alert anxiety. A tool that constantly reminds me about every recurring charge could make ordinary spending feel like a problem. I prefer a calmer approach: use the app to identify commitments, then judge them by actual value. Keeping a subscription is not failure if it genuinely supports my work, health, entertainment, or family life. The point is visibility, not guilt.
The third is the gap between seeing a service and ending it. If cancellation requires several steps elsewhere, the momentum can disappear. My practical workaround would be to review subscriptions when I have enough time to complete the next action, not while rushing between tasks. I would also write down the provider’s cancellation route or confirmation details where appropriate, so the review leads to a finished result.
Paid options create another decision point. The app itself is free, but optional purchases can cost from $4.99 to $99.99 per item. I would not pay simply because I had installed it. I would first use the free experience long enough to determine whether the app actually improves my review habit. The right purchase is one that removes a recurring obstacle in my workflow, not one made during the initial excitement of finding forgotten subscriptions.
That pricing range also means different users may reach different conclusions. Someone with only a few subscriptions and a reliable manual system may not see enough benefit to justify spending more. Someone managing many recurring services may value a dedicated tool more strongly, provided the paid features match the way they review expenses. I would make that decision based on repeated usefulness, not on the number of features visible on the first day.
Who should keep Subpilot installed?
I would recommend it most readily to people who have accumulated several subscriptions, regularly forget renewal dates, or feel that their bank statement is too scattered to interpret quickly. It is especially suitable for anyone who wants a focused finance app rather than a large budgeting suite. New users can start with a simple audit, while more organized users can treat it as a recurring checkpoint.
It may also suit people who are about to simplify their finances. A student finishing a course, a household reducing discretionary spending, or a professional reviewing software expenses can use a subscription list to separate active needs from temporary habits. The app is not limited to entertainment services; the broader value comes from seeing any repeating commitment together.
I would be less enthusiastic for someone who has one or two subscriptions, checks every payment manually, and already knows exactly where to cancel each one. In that situation, the extra app may create more administration than savings. I would also look elsewhere if my main goal were investment tracking, debt payoff planning, income forecasting, or detailed category budgeting. Those tasks need a broader financial system.
People expecting automatic cancellation without any outside steps should also adjust their expectations. The app’s usefulness comes from organizing attention and supporting decisions, not from making every provider follow one universal process. If a subscription is difficult to cancel, I would still need patience and a final verification after taking action.
The age rating of Everyone makes the app approachable for a broad audience, but suitability still depends on financial circumstances and comfort with digital tools. A young user learning to manage recurring payments might benefit from the visibility, while a family could use it as part of a shared review. In both cases, I would explain that the app is a guide to commitments, not a substitute for checking actual account activity.
My long-term verdict after the novelty fades
Subpilot earns lasting space when it becomes a monthly decision tool, not when it remains a one-time cleanup app. That is my central judgment. The first-week experience is appealing because it turns hidden or forgotten subscriptions into something I can examine. The month-to-month case is stronger when I use it before adding services, during life changes, and as a prompt to verify cancellations.
I appreciate the focused purpose. Linerios Limited has positioned this as a finance app for tracking and cancelling subscriptions, and that narrow scope makes it easier to understand than a platform trying to handle every money problem at once. The 4.1 average from roughly 1.7 thousand written reviews gives it a credible, though not flawless, reception. I read that as a reason to try it thoughtfully rather than as a guarantee that every workflow will suit every user.
My reservations are practical rather than dramatic. The app cannot eliminate the need to check original providers, verify charges, or maintain accurate records. Repeated reviews can become tiring, and optional purchases deserve careful consideration because the available price range is wide. Anyone who dislikes adding another financial tool to their routine may find a spreadsheet or direct account management simpler.
Still, I think the app has a clear place for people who repeatedly lose track of recurring payments. Its best contribution is not a flashy financial dashboard; it is the pause it creates before another renewal passes unnoticed. If I were recommending it to a friend, I would say: install it for a focused subscription audit, compare what it shows with your statements, and keep it only if it makes your monthly money check easier to complete.
Subpilot is free to start, available for Android 8.0 and later, and currently listed as version 1.24.1. I would judge it after several review cycles, not after the first satisfying cancellation. If it helps you notice changes, avoid duplicate services, and follow through on decisions without adding more stress, it can justify a permanent place on your phone. If it only repeats information you already manage well, uninstalling it is the more sensible financial decision.
Subpilot FAQ
What is Subpilot and what can I use it for?
Subpilot is designed to help users keep track of recurring subscriptions and other regular payments in one place. After adding your services, you can review upcoming charges, monitor spending, and identify subscriptions you may no longer need. It is particularly useful if you have memberships across different platforms and want a clearer overview of renewal dates and monthly costs.
Does Subpilot automatically detect all of my subscriptions?
Subpilot’s ability to identify subscriptions depends on the information and account access you provide, as well as the financial institutions or services supported by the app. Some recurring payments may need to be added manually, especially subscriptions billed through a different card, app store, or payment provider. Always review the detected entries and correct names, prices, and renewal dates when necessary.
Is Subpilot safe to use with my financial information?
Before connecting any financial account, users should review Subpilot’s privacy policy, security documentation, and the permissions requested during setup. Financial data may be processed through third-party connectivity providers, depending on the region and integration used. Avoid sharing banking passwords outside the official connection screen, enable available security features, and disconnect accounts if you stop using the service.
Can Subpilot cancel subscriptions for me?
Subpilot may help you find recurring services and provide information or guidance for managing them, but cancellation capabilities can vary by subscription provider and region. Many subscriptions still require you to cancel directly through the company’s website, Google Play, Apple App Store, or another billing platform. Check the cancellation instructions carefully and confirm that you receive a successful cancellation notice.
Is Subpilot free, and are there any limitations?
The availability of free features, premium tools, trial periods, and subscription charges can change over time and may differ between Android, iOS, and specific countries. Check the current listing and in-app pricing before creating an account or starting a trial. Pay attention to renewal terms, billing frequency, and cancellation deadlines so you are not charged unexpectedly after a promotional period ends.











